The short answer
Equipment financing spreads the cost of excavators, loaders, trucks and other machinery over the machine's working life so it earns while you pay for it. Most lenders finance new and used machinery, with used equipment sometimes limited by age or hours.
Key takeaways
- If a machine works more than a few months each year, financing usually costs less than renting over the long run.
- Lenders look at resale value, the owner's credit, time in business and cash flow stability, including backlog and signed contracts.
- Map expected progress payments against the payment schedule before choosing terms.
- Ask your accountant about Section 179 before signing, especially near year-end.
| Structure | What you get | Fits |
|---|---|---|
| Equipment loan or finance lease | Ownership and the machine after the term | Core equipment used for years |
| Operating or FMV lease | Lower payments; return, renew or buy | Specialized equipment for a limited number of projects |
| Short-term rental | No commitment | A one-off job; costly if repeated |
Why construction companies finance equipment
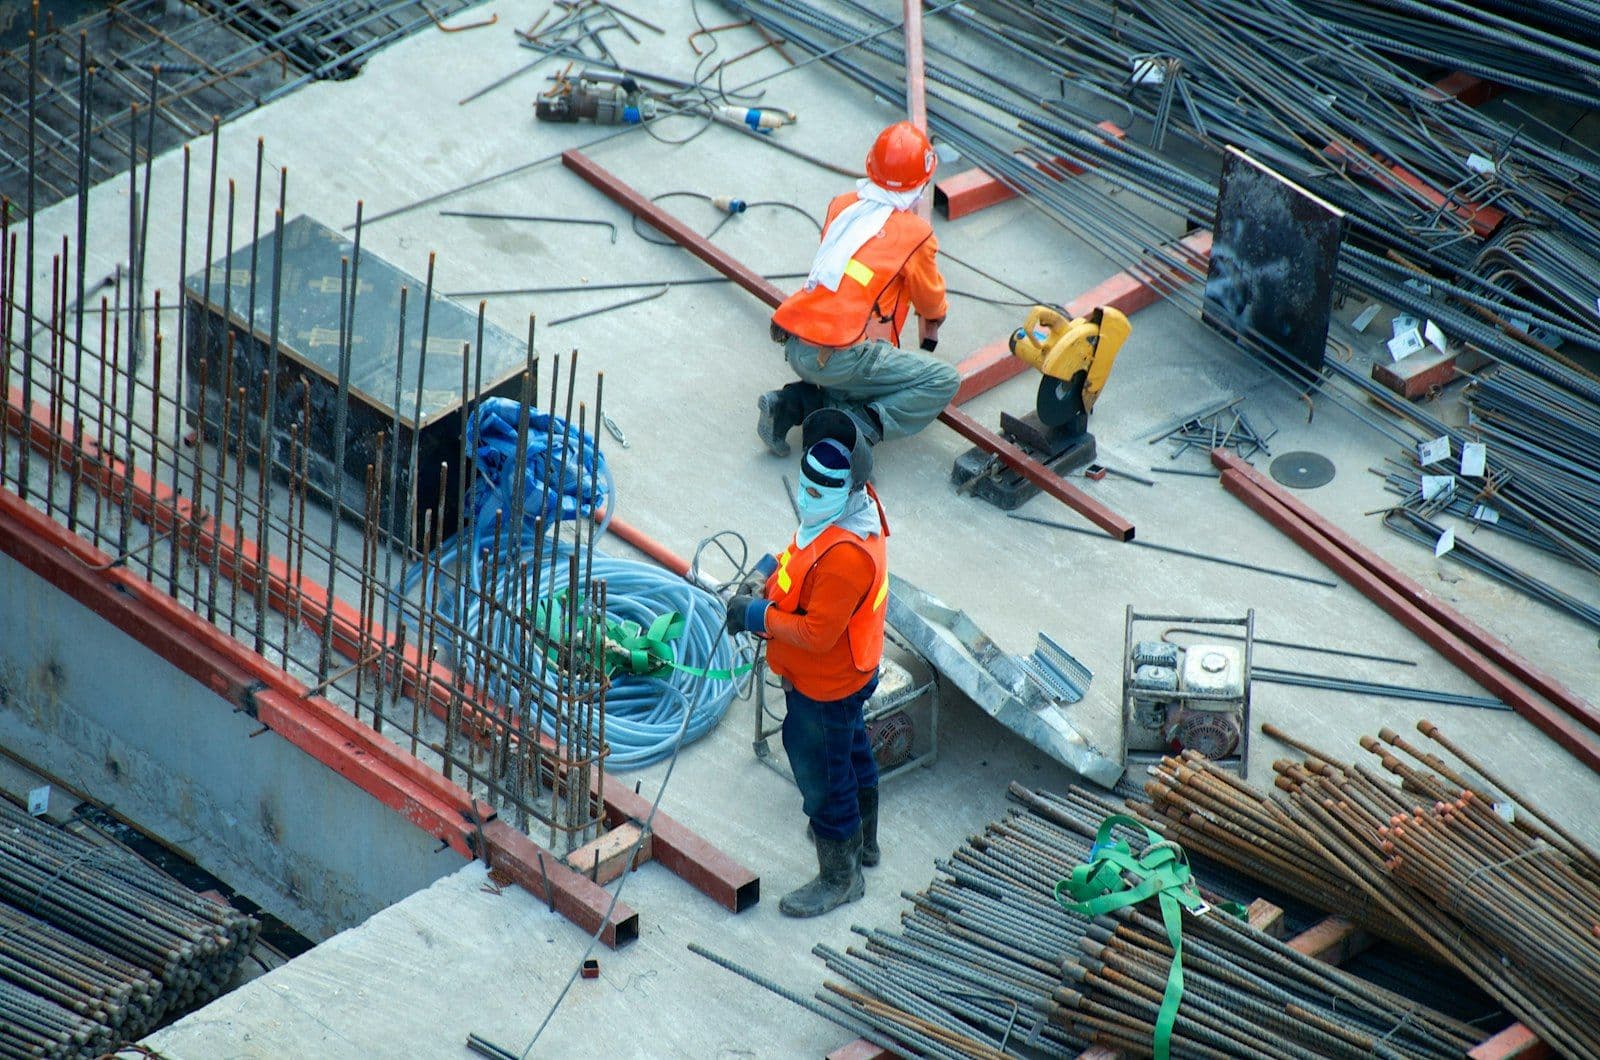
Excavators, skid steers, loaders, cranes, dump trucks and compaction equipment cost far more than most contractors want to pay in cash. Buying outright can consume the working capital needed for payroll, materials and bonding, and a bid won or lost can depend on having the right machine.
Equipment financing spreads the cost over the working life of the machine so the equipment earns while you pay for it.
What can be financed
Most lenders will finance both new and used machinery, including:
- Excavators, backhoes, skid steers and compact track loaders.
- Dozers, graders, loaders and compactors.
- Dump trucks, flatbeds, trailers and service vehicles.
- Cranes, lifts and concrete equipment.
- Attachments such as buckets, breakers and augers.
- Surveying and technology equipment.
Used equipment is often financeable, but lenders may limit the age or hours, shorten the term and ask for a larger down payment.
Financing, leasing or a rental-purchase structure
- Equipment loan or finance lease: you build ownership and keep the machine after the term. This usually fits core equipment you will use for years.
- Operating or FMV lease: lower payments and an option to return, renew or buy. This can suit specialized equipment you need for a limited number of projects.
- Short-term rental: sensible for a one-off job, though costly if repeated.
If a machine will be working more than a few months each year, financing usually costs less than renting over the long run.
How lenders evaluate construction businesses
Lenders look at the equipment's value and resale market, the owner's credit, time in business and the stability of cash flow. They know construction revenue is uneven, so they pay attention to backlog, signed contracts and the pattern of deposits over time.
Equipment with strong resale value, such as common brands and models in good condition, tends to get better terms because it is easier to recover value if something goes wrong.
Matching terms to project cash flow
Construction cash arrives in waves: progress payments, retainage and slow-paying general contractors. Before choosing a payment schedule, map expected receipts against the payment.
- A longer term lowers the monthly payment but costs more in total interest.
- A seasonal or step-up structure, where available, can match slower winter months.
- Keep a reserve to cover payments if a progress payment is late.
Avoid structures that require weekly payments unless your cash flow is predictable week to week.
Tax considerations to discuss with your accountant
Financed equipment may qualify for Section 179 expensing or depreciation, subject to annual limits, asset type and eligibility. Because the rules and limits change and depend on your situation, ask your accountant before signing, particularly when buying near year-end.
Application checklist for contractors
- Dealer quote or invoice for the machine, including attachments.
- Three to six months of business bank statements.
- Business tax returns or year-end financials.
- Current backlog or signed contracts, if available.
- Insurance details for the equipment.
lendfloCapital matches contractors with equipment financing through one short application, with no cost to apply and a soft credit pull for the initial review.
lendfloCapital
Ready to put this knowledge to work?
Tell us about your business and a lendfloCapital advisor will review your options and walk you through what fits.
Frequently asked questions
Can I finance used construction equipment?
Often yes, but lenders may limit the age or hours, shorten the term and ask for a larger down payment.
How do lenders evaluate a construction company?
They look at the equipment's value and resale market, the owner's credit, time in business and cash flow stability. Because construction revenue is uneven, they also pay attention to backlog, signed contracts and deposit patterns.
What documents do contractors need?
A dealer quote or invoice, three to six months of business bank statements, tax returns or year-end financials, current backlog or signed contracts if available, and insurance details for the equipment.